Seguro de casa en Texas, explicado en español y comparado entre varias aseguradoras.
Home insurance in Texas, explained in Spanish and compared across several insurers.
Tu casa es probablemente lo más grande que tienes. Te ayudamos a escoger el seguro (o aseguranza) de casa correcto según su edad, su techo y su zona, y te explicamos el deducible de viento y granizo antes de que lo necesites, no después.
Your home is probably the biggest thing you own. We help you insure it with the right policy for its age, its roof and its area, and we explain the wind and hail deductible before you need it, not after.
En Texas, el precio de tu casa depende del techo y del granizo
In Texas, your home's price depends on the roof and on hail
En Texas no todas las aseguradoras aceptan todas las casas. Una casa nueva en buen estado tiene muchas opciones; una casa de 30 o 50 años, o con un techo viejo, tiene menos, y ahí es donde un agente independiente hace la diferencia. Además, casi todas las pólizas en Texas tienen un deducible de viento y granizo en porcentaje, que puede ser mucho más alto que el deducible normal. Antes de cotizar revisamos la edad de tu casa, el techo, las actualizaciones (plomería, electricidad, aire acondicionado) y tu historial de reclamos, y buscamos el mercado que mejor acepta tu tipo de casa. Así no te llevas sorpresas cuando llegue una tormenta.
In Texas, not every insurer accepts every home. A new home in good condition has many options; a 30- or 50-year-old home, or one with an old roof, has fewer, and that is where an independent agent makes the difference. Almost every Texas policy also carries a percentage wind and hail deductible, which can be much higher than the regular deductible. Before quoting, we review the age of your home, the roof, updates (plumbing, electrical, A/C) and your claims history, and we look for the market that best accepts your type of home. That way there are no surprises when a storm hits.
Seguro de casa para cada tipo de casa en Texas
Home insurance for every kind of Texas home
- Casas nuevas o casi nuevas (0 a 10 años): son las que más opciones tienen y donde más se puede comparar precio y cobertura.
- Casas de 11 a 40 años: con techo y sistemas al día todavía califican en buenos mercados; te decimos qué actualizaciones ayudan.
- Casas de más de 40 años o de menor valor: trabajamos mercados que aceptan casas viejas, aunque la cobertura del techo pueda ser distinta.
- Dueños con hipoteca: tu banco exige seguro y te pide la póliza o la evidencia de cobertura antes de cerrar o renovar.
- Dueños de condominio: un condo usa una póliza HO-6 que cubre el interior de tu unidad y tus cosas, no el edificio completo.
- Si tu aseguradora no te renovó: te ayudamos a recolocar la casa en otro mercado antes de que se venza la póliza.
- New or nearly new homes (0 to 10 years): they have the most options and the most room to compare price and coverage.
- Homes 11 to 40 years old: with an updated roof and systems they still qualify for good markets; we tell you which updates help.
- Homes over 40 years old or of lower value: we work with markets that accept older homes, even if roof coverage may be different.
- Owners with a mortgage: your lender requires insurance and asks for the policy or evidence of coverage before closing or renewal.
- Condo owners: a condo uses an HO-6 policy that covers the inside of your unit and your belongings, not the whole building.
- If your insurer did not renew you: we help you place the home with another market before the policy expires.
Lo que revisamos en tu póliza de casa.
What we review in your home policy.
Dwelling (la estructura)
Dwelling
Paredes, techo, pisos y lo que está fijo a la casa. El límite debe alcanzar para reconstruirla, no lo que pagaste por ella.
Walls, roof, floors and everything attached to the house. The limit should cover rebuilding it, not what you paid for it.
Otras estructuras
Other Structures
Cercas, garaje separado, cuarto de herramientas o carport que no están pegados a la casa.
Fences, a detached garage, a shed or a carport that is not attached to the house.
Tus pertenencias (Personal Property)
Personal Property
Muebles, ropa, electrónicos y más. Pregunta si es a valor de reemplazo (Replacement Cost) o a valor depreciado (ACV).
Furniture, clothing, electronics and more. Ask whether it pays Replacement Cost or depreciated value (ACV).
Responsabilidad civil (Liability)
Personal Liability
Si alguien se lastima en tu casa o tú causas daño a otra persona, cubre la reclamación y tu defensa legal.
If someone is hurt at your home or you damage someone else's property, it covers the claim and your legal defense.
Gastos adicionales de vida (Loss of Use)
Loss of Use / ALE
Hotel, renta temporal y comida extra si tu casa no se puede habitar después de un daño cubierto.
Hotel, temporary rent and extra meals if your home is unlivable after a covered loss.
Techo y deducible de viento y granizo
Roof and wind/hail deductible
Revisamos si el techo se paga a valor de reemplazo o a ACV, y cuánto es tu deducible de viento y granizo en dólares.
We check whether the roof is paid at replacement cost or ACV, and how much your wind/hail deductible is in dollars.
Lo que pasa de verdad con las casas en Texas.
What really happens to homes in Texas.
Granizo en Dallas o Fort Worth
Hail in Dallas or Fort Worth
Una tormenta daña el techo. Si tu deducible es 2% sobre una casa de $300,000, tú pagas los primeros $6,000. Mejor saberlo hoy.
A storm damages the roof. If your deductible is 2% on a $300,000 home, you pay the first $6,000. Better to know it today.
Una tubería que revienta
A burst pipe
Una helada rompe una tubería y el agua daña pisos y paredes. El daño repentino suele estar cubierto; la fuga lenta de meses normalmente no.
A freeze bursts a pipe and water damages floors and walls. Sudden damage is usually covered; a slow leak over months usually is not.
La aseguradora no te renueva
Your insurer does not renew
Por la edad del techo o por cerrar tu zona, te llega un aviso de no renovación. Comparamos otros mercados antes de que te quedes sin cobertura.
Because of roof age or because your area closed, you get a non-renewal notice. We compare other markets before you are left uncovered.
Un invitado se cae en tu casa
A guest falls at your home
Alguien se resbala en tus escaleras y tiene gastos médicos. La responsabilidad civil de tu póliza responde por ti.
Someone slips on your stairs and has medical bills. Your policy's liability coverage responds for you.
Lo que necesitamos para cotizarte.
What we need to quote you.
- La dirección de la casa y si vives en ella.
- Año de construcción, pies cuadrados y año en que se cambió el techo.
- Actualizaciones de plomería, electricidad y aire acondicionado, si las tienes.
- Tu póliza actual (dec page) o la fecha en que se vence.
- Reclamos de casa en los últimos 5 años y el nombre de tu banco si tienes hipoteca.
- The home's address and whether you live in it.
- Year built, square footage and the year the roof was replaced.
- Plumbing, electrical and A/C updates, if any.
- Your current policy (dec page) or its expiration date.
- Home claims in the last 5 years and your lender's name if you have a mortgage.
La cobertura, los requisitos y los costos dependen de la aseguradora, la propiedad o el negocio y los términos de cada póliza. Esta página es informativa y no sustituye el texto de una póliza.
Coverage, requirements and costs depend on the insurer, the property or business and each policy's terms. This page is informational and does not replace policy language.
Lo que preguntan nuestros clientes.
What our clients ask.
Un seguro de casa (Homeowners) cubre la estructura, otras estructuras como cercas, tus pertenencias, tu responsabilidad civil y los gastos de vivir fuera si la casa queda inhabitable por un daño cubierto. Los límites, el deducible y cómo se paga el techo cambian según la aseguradora, por eso comparamos varias opciones.
A homeowners policy covers the structure, other structures like fences, your belongings, your personal liability and the cost of living elsewhere if the home is unlivable after a covered loss. Limits, deductibles and how the roof is paid vary by insurer, which is why we compare several options.
Es un deducible que se calcula como un porcentaje del límite de Dwelling, no como una cantidad fija. Si tu casa está asegurada por $300,000 y el deducible es 1%, pagas $3,000 de un reclamo de granizo; si es 2%, pagas $6,000. En Texas suele estar entre 1% y 3%, y en algunas zonas está subiendo.
It is a deductible calculated as a percentage of your Dwelling limit, not a fixed amount. If your home is insured for $300,000 and the deductible is 1%, you pay $3,000 of a hail claim; at 2%, you pay $6,000. In Texas it is usually between 1% and 3%, and it is rising in some areas.
Sí, en muchos casos. Hay aseguradoras que trabajan casas viejas o de menor valor, aunque pueden pagar el techo a valor depreciado (ACV) o pedir fotos e inspección. Entre más actualizaciones tenga la casa (techo, plomería, electricidad), más opciones y mejor precio vas a encontrar.
Yes, in many cases. Some insurers work with older or lower-value homes, although they may pay the roof at depreciated value (ACV) or ask for photos and an inspection. The more updates the home has (roof, plumbing, electrical), the more options and the better price you will find.
ACV (Actual Cash Value) significa que la aseguradora paga el techo descontando la depreciación por edad. En un techo de 15 años, el pago puede ser bastante menor que lo que cuesta un techo nuevo. Con valor de reemplazo (Replacement Cost) se paga el costo de reponerlo, menos tu deducible.
ACV (Actual Cash Value) means the insurer pays the roof minus depreciation for its age. On a 15-year-old roof, the payment can be much less than the cost of a new roof. With Replacement Cost, it pays the cost of replacing it, minus your deductible.
No. El seguro de casa normal no cubre inundación (flood), ni por lluvia que entra desde afuera ni por agua que sube. La inundación se asegura con una póliza aparte. Lo que sí suele cubrir es el daño repentino de agua desde adentro, como una tubería que revienta.
No. A standard home policy does not cover flood, whether from rising water or surface water coming in from outside. Flood is insured with a separate policy. What it usually does cover is sudden water damage from inside, like a burst pipe.
Sí. Un condo usa una póliza HO-6, que cubre el interior de tu unidad, tus pertenencias y tu responsabilidad civil. El edificio y las áreas comunes los cubre la póliza de la asociación (HOA). Revisamos las reglas de tu asociación para saber desde dónde empieza tu responsabilidad.
Yes. A condo uses an HO-6 policy, which covers the inside of your unit, your belongings and your liability. The building and common areas are covered by the association's (HOA) master policy. We review your association's rules to see where your responsibility begins.
Sí. Todo el proceso, desde la cotización hasta un reclamo, en español o en inglés. Aseguramos casas en todo Texas, con la mayoría de nuestros clientes en Dallas, Fort Worth y sus alrededores, y también en Houston, San Antonio, Austin y el resto del estado.
Yes. The whole process, from quote to claim, in Spanish or English. We insure homes across Texas, with most of our clients in Dallas, Fort Worth and nearby cities, and also in Houston, San Antonio, Austin and the rest of the state.
Otros seguros que trabajamos.
Other coverage we write.
Viento y GranizoWind & Hail
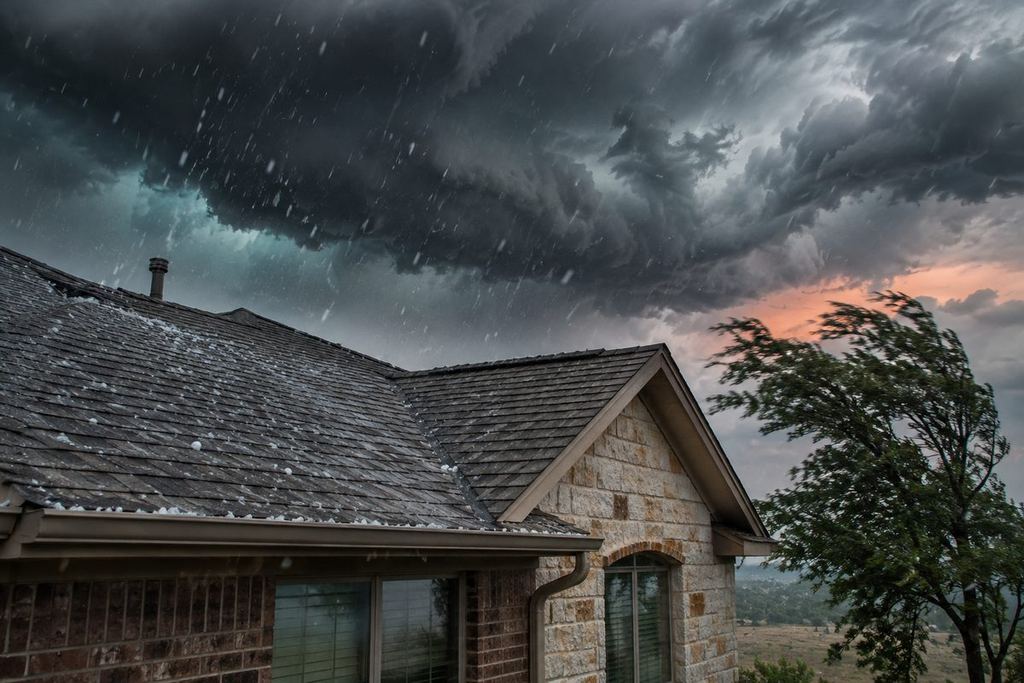
Entiende tu deducible de viento y granizo en dólares y qué pasa con tu techo después de una tormenta.
Understand your wind and hail deductible in dollars and what happens to your roof after a storm.
Ver cobertura y preguntas →See coverage & FAQs →
Seguro de AutoAuto Insurance
Liability, full coverage, SR-22 y opciones con licencia de otro país.
Liability, full coverage, SR-22 and options with a foreign license.
Ver cobertura y preguntas →See coverage & FAQs →
Seguro de JoyasJewelry Insurance
Anillos, cadenas y relojes asegurados por su avalúo (jewelry floater).
Rings, chains and watches insured at appraised value (jewelry floater).
Ver cobertura y preguntas →See coverage & FAQs →